PM-MKSSY: Can Insurance Make Aquaculture More Resilient?
Opinion | As India’s aquaculture sector expands, affordable insurance and faster claims could determine whether farmers can withstand the next big loss

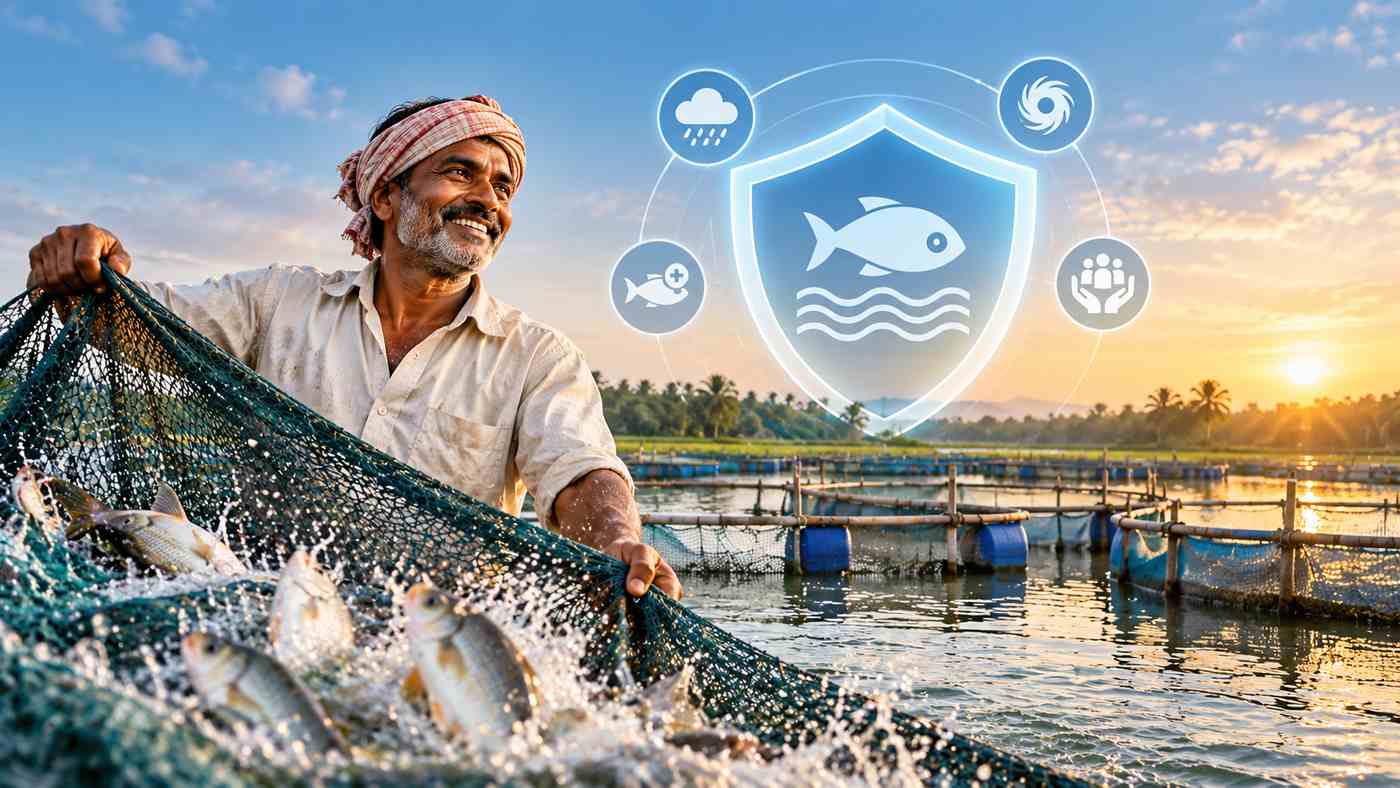
India’s aquaculture sector has grown from a relatively modest rural activity into an increasingly important part of the country’s food, employment and export economy. But growth has also brought a difficult question to the surface: what happens when an entire crop is lost?
For a farmer who has invested months of labour and borrowed money to stock a pond, a disease outbreak, flood, cyclone or other unforeseen event is not simply an agricultural setback. It can mean the loss of an entire season’s income and, in some cases, the beginning of a much deeper financial crisis.
This is where the Pradhan Mantri Matsya Kisan Samridhi Sah-Yojana (PM-MKSSY) enters the picture.
The government’s aquaculture insurance initiative is built around a fairly straightforward idea: farmers cannot always prevent losses, but they should have a mechanism to recover financially when insured risks materialise.
That idea is particularly relevant as India’s fish production continues to expand. According to the figures cited in the government material, total fish production increased from 9.6 million tonnes in 2013–14 to 19.8 million tonnes in 2024–25. Inland fish production also rose to 14.74 million tonnes during 2024–25.
Aquaculture accounts for more than 74% of India’s total fish production, making risk management in the sector increasingly important.
Growth brings a bigger exposure to risk
The impressive expansion of aquaculture should not obscure the risks faced by farmers.
Disease outbreaks can destroy stocks within a short period. Floods and cyclones can damage ponds and infrastructure, while pollution and extreme weather can affect production even when farmers have followed normal management practices.
For small and marginal farmers, the consequences can be particularly severe because their ability to absorb a sudden financial loss is limited.
Insurance, therefore, has a role that goes beyond compensation. Properly designed and efficiently implemented, it can provide farmers with the confidence to continue investing after a bad production cycle rather than abandoning aquaculture altogether.
But this is also where the real test for PM-MKSSY begins.
Making insurance affordable is only the first step
Under PM-MKSSY, eligible aquaculture farmers can receive a one-time incentive of up to 40% of the insurance premium for one crop cycle through Direct Benefit Transfer.
For pond-based aquaculture, the incentive is capped at ₹25,000 per hectare of water-spread area, with a maximum incentive of ₹1 lakh for up to four hectares. Farmers with holdings below one hectare are eligible on a pro-rata basis.
For advanced systems such as cage culture, Recirculatory Aquaculture Systems, biofloc and raceways, the scheme provides an incentive of 40% of the premium, subject to specified limits.
Additional support is available for SC, ST and women beneficiaries.
These provisions address one of the most obvious barriers to insurance adoption — the cost of the premium.
Yet affordability alone does not guarantee adoption.
A farmer is likely to continue purchasing insurance only if the experience of making a claim is straightforward, transparent and predictable.
The real test will come when claims are filed
The success of any insurance programme ultimately depends on what happens after a loss.
Under the scheme, farmers must notify the insurance company when an insured event occurs and provide the required documentation. The insurer then appoints a loss assessor to evaluate the damage before processing the claim.
The prescribed timeline is 30 days for shrimp culture and 45 days for other aquaculture activities.
On paper, these timelines provide a clear framework. On the ground, however, farmers will judge the system by how easily they can report losses, how quickly assessments are conducted and whether settlements arrive when they are actually needed.
This is particularly important in aquaculture because losses can be time-sensitive. A delayed assessment can complicate the process of determining the extent and cause of damage.
Technology can potentially make a difference here. Digital records, satellite and remote-sensing tools, farm-level data and better disease surveillance could gradually make assessment more transparent and reduce disputes. But technology will have to complement, rather than complicate, the farmer’s experience.
Early numbers show interest, but also room for expansion
The implementation figures cited by the government show that the insurance component has begun to attract participation.
A total of 316 One-Time Incentive applications had been received, covering 730.61 hectares. Of these, 127 applications had been approved and disbursed, covering 321.74 hectares, with total disbursement of ₹40.03 lakh.
These numbers indicate that the mechanism is being used, but they also underline the scale of the task ahead when compared with the size of India’s aquaculture sector.
Four insurers — OICL, AICL, NIAL and UIIC — are currently operational under the initiative, with private insurers also being onboarded.
A broader insurance ecosystem could potentially give farmers more product choices. But greater participation by insurers will matter only if it translates into products that farmers understand, can afford and can actually use when losses occur.
From subsidy to sustainable insurance
The larger objective should be to ensure that aquaculture insurance eventually becomes a normal component of farm management rather than something farmers adopt only because a government incentive is available.
That transition will require coordination.
The Centre has a role in policy design and digital infrastructure. State governments will be important for local outreach and implementation. Insurers will have to develop products suited to different aquaculture systems and risk profiles. Farmers, meanwhile, need clear information about coverage, exclusions, premiums and claim procedures.
Technical institutions can also contribute by improving disease surveillance, risk mapping and loss assessment.
The biggest challenge may ultimately be one of trust.
Farmers will not judge insurance by the language of a policy document. They will judge it by what happens after a cyclone hits, a disease destroys a pond or an unexpected event wipes out months of investment.
If claims are handled fairly and within the promised timelines, confidence can grow. If procedures become complicated or settlements are delayed, adoption could remain limited despite financial incentives.
A safety net for the Blue Revolution
India’s aquaculture expansion has created new opportunities for rural employment, food production and exports. But a growing sector also needs mechanisms that protect the people taking the production risks.
PM-MKSSY’s aquaculture insurance component addresses an important gap by making insurance more affordable and creating a structured framework for risk protection.
The next stage is implementation.
The real measure of the scheme will not simply be how many policies are sold or how much premium support is provided. It will be whether a farmer facing a devastating loss can access the promised protection without unnecessary delay or uncertainty.
For India’s Blue Revolution to remain sustainable, farmers will need not only access to markets and technology, but also the confidence that one bad season will not wipe out everything they have built.
